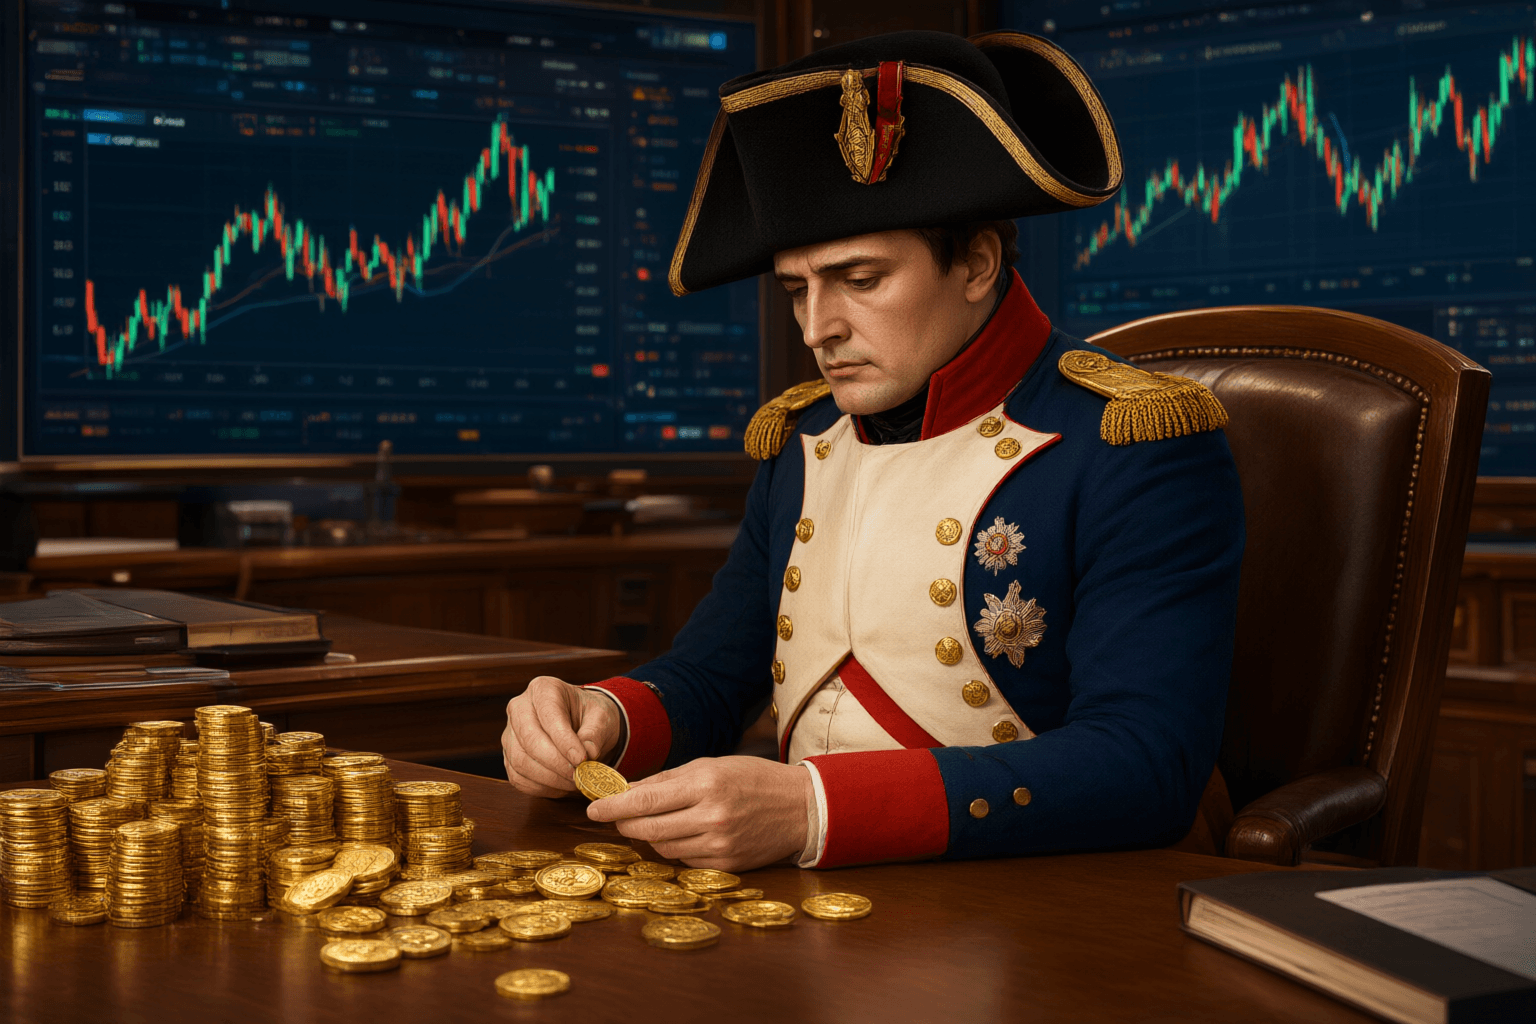
In 1810, Britain was on the brink of famine. The Continental Blockade had cut grain imports from Europe from 114,000 tons in 1807 to just 14,000 tons in 1808. Wheat prices had risen nearly 60%. Napoleon had Britain by the throat. And then he authorized French and allied grain exports to his enemy — not out of mercy, but because he wanted their gold. Mercantilism, the dominant economic framework of 18th-century Europe, measured national wealth in precious metals, in 'specie'. In the logic of the system, a starving Britain paying gold for French wheat was a French victory. Napoleon was not subordinating strategy to accounting — he believed the gold was the strategy. Drain the enemy of specie and you drain them of the means to wage war.
Britain issued bonds, paid in gold, survived the blockade, financed another coalition, and Napoleon's empire collapsed four years later. The framework had mistaken the scoreboard for the game.
The confusion did not die at Waterloo. It mutated, resurfacing two centuries later in a form so familiar that most people working inside it cannot see its edges. Shareholder value maximization — the doctrine that a corporation's sole responsibility is to increase its profits, articulated by Milton Friedman in 1970 and operationalized through stock-based compensation, quarterly earnings guidance, dividends, and the buyback — treats accounting profits and share price as the ultimate score, just as mercantilism treated gold. The financial metric is the goal, not the measure. What happens to the real productive base is, by design, someone else's problem.
Discussion